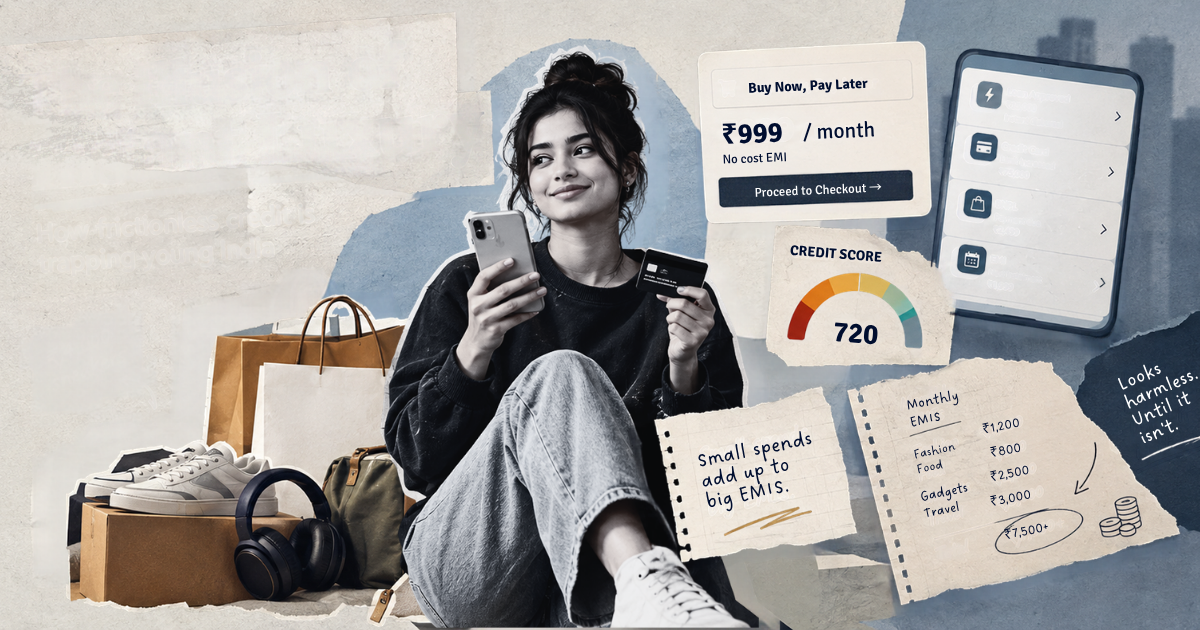
At 23, financial independence used to mean managing an entry-level salary and saving for goals. Today, Buy Now, Pay Later (BNPL) platforms, instant loan apps, and credit cards turn lifestyle wants—a ₹4,000 sneaker haul or a ₹15,000 weekend trip—into frictionless “₹999/month” instalments. What feels like convenience is quietly morphing into a long-term debt trap for India’s Gen Z and young millennials.
The Numbers Behind the Debt Cycle
Data from credit bureaus (CIBIL, CRIF High Mark) and the RBI highlights a rapid shift in young borrowing habits:
- Mass Adoption: Borrowers under 30 account for 41% of all new credit entrants, with 57% obtaining their first credit card before age 28.
- Multi-App Stacking: Nearly 30% of 20–30-year-olds carry active balances across two or more credit platforms simultaneously.
- Early Delinquency: Early-stage overdues (30–90 days past due) in retail credit are highest among borrowers under 25.
- High Interest Escalation: Revolving balances on unpaid cards trigger interest rates of 36% to 48% annually, severely damaging credit scores right at the start of young careers.
The Psychology: “Frictionless” Spending and Silent Debt
The core danger of modern credit isn’t just high interest—it’s psychological frictionlessness.
When using cash or debit, the brain registers the “pain of paying.” BNPL and 1-tap in-app credit sever this emotional check. Because young consumers often view BNPL as a payment feature rather than a formal loan, spending becomes impulse-driven.
Micro-commitments—₹1,200 for fast fashion, ₹800 for quick commerce, and ₹2,500 for a gadget EMI—seem harmless in isolation. Combined, this silent debt easily consumes 35% to 50% of an entry-level salary, leaving zero room for emergency savings or wealth-building equity investments.
3 Steps to Break Free
- Enforce the 24-Hour Cool-Off Rule: Force a mandatory 24-hour waiting period on non-essential purchases over ₹2,000 to eliminate impulse buying.
- Purge Micro-Credit Apps: Unlink auto-checkout BNPL options from food delivery, travel, and shopping apps. Consolidate spending to a single debit or credit card.
- Cap Debt at 30% of Income: Ensure total monthly EMIs and credit card obligations never exceed 30% of net monthly take-home pay.
Aakarsh Dalmia
Certified Financial Planner CFPCM
Instagram ID -wealthwithaakarsh